Every time a quiet neighborhood fixture passes away and leaves millions to charity, the media rolls out the same tired sermon. They call it the triumph of frugal living. They point to the decades-old sedan, the patched flannel shirts, and the coupons clipped from Sunday circulars. They want you to believe that the path to a thirteen-million-dollar estate is just a matter of skipping your morning latte and compounding interest in an index fund for forty years.
It is a comforting myth. It lets society pretend that wealth accumulation is an egalitarian meritocracy where anyone who eats enough beans and rice can quietly amass a fortune.
It is also complete garbage.
I have spent decades watching ordinary people grind themselves down in the name of this ascetic fantasy, and the math tells a brutal truth. When an unassuming retiree hoards millions while living like a pauper, you are not looking at a masterclass in personal finance. You are looking at a glaring symptom of structural distortion, catastrophic tax policy anomalies, and a real estate market that inflated past all rational bounds while wages flatlined.
Let us dismantle the narrative piece by piece.
The Cult Of Thrift Hides The Real Engine
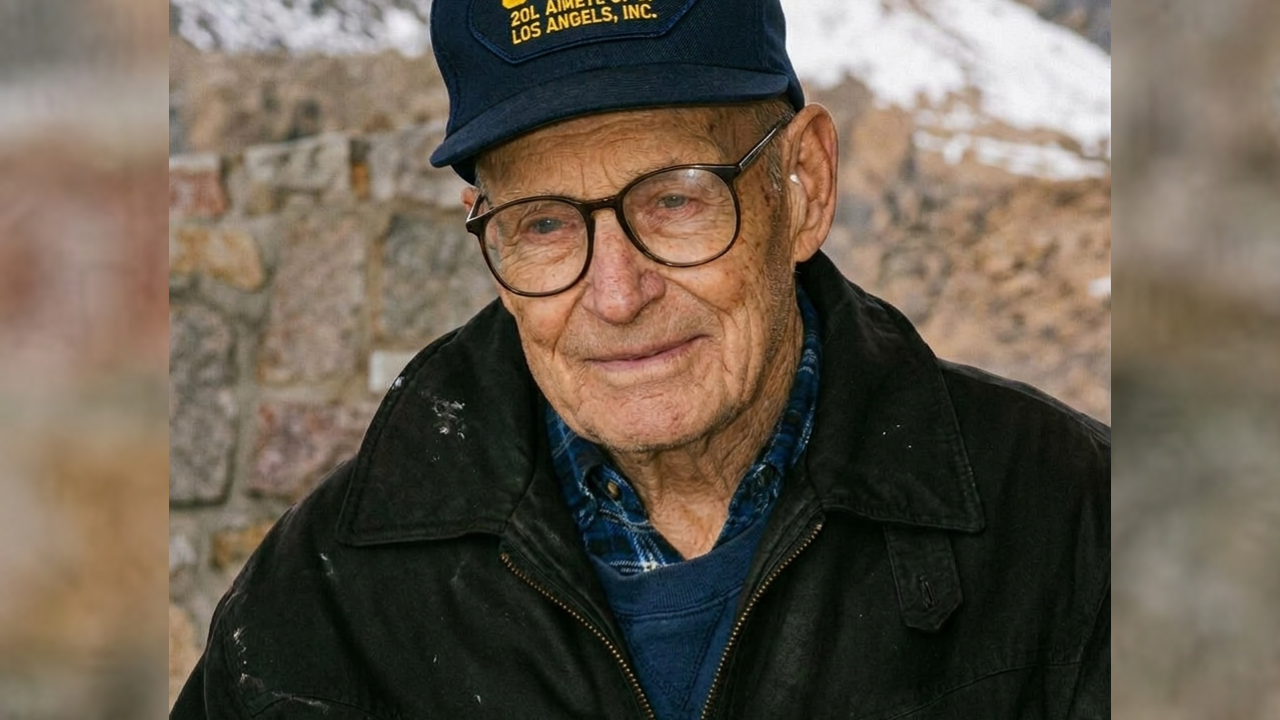
The standard take on the Indianapolis man who left a staggering sum behind frames his accumulation as an act of pure willpower. He saved. He invested. He stayed out of debt.
Nobody ever asks the obvious question: Why did he need thirteen million dollars just to die?
If you accumulate thirteen million dollars while maintaining a frugal lifestyle, you did not just save money. You actively extracted capital from circulation without deploying it into productive enterprise, community building, or even your own quality of life. You hoarded claims on future labor.
The lazy consensus treats frugality as the primary variable in the wealth equation. It is not. Income generation, asset appreciation driven by monetary policy, and geographic luck dwarf the money you save on groceries every single week. A person saving five hundred dollars a month on a modest salary cannot out-save structural asset inflation unless they bought a plot of land in a booming metro area forty years ago and watched zoning laws turn it into a goldmine.
That is what actually happened. The millions did not come from clipping coupons. They came from long-term asset positioning in a housing market that decoupled from reality, coupled with a stock market fueled by cheap liquidity. Attributing that windfall to self-denial is like praising a guy for winning the lottery because he carefully filled out his ticket with a number two pencil.
The Moral Hazard Of Hoarding
We love these stories because they make us feel safe. A billionaire hedge fund manager flashing yachts makes people angry. A quiet guy in a modest suburban home leaving millions to a local charity makes people weep. It feels noble.
It is actually tragic.
Think about the human cost of that thirteen-million-dollar pile. To accumulate that sum through quiet accumulation and basic living, a person has to suppress consumption for an entire lifetime. They trade experiences, comfort, health, and community impact for a number on a brokerage statement. They live small so their estate can be large.
And for what? So that a charity can receive a lump sum decades after the economic utility of that money could have actually mattered. Capital is meant to be a circulating medium of exchange and productive risk. When it gets locked inside the mattress of a conservative portfolio and left to sit until death, it represents stagnant economic energy.
I have seen small business owners do this for thirty years. They starve their operations of reinvestment, pay themselves garbage wages, and treat every dollar spent on employee retention or operational upgrades as a personal insult. They die rich and miserable, leaving heirs or charities scrambling to deal with assets that should have been put to work decades earlier.
The Asset Bubble Blindspot
Let us look at the mechanics of how ordinary people actually hit these numbers today. You cannot do it through savings accounts. You cannot do it through safe municipal bonds.
To turn modest earnings into millions, you need leverage, massive asset appreciation, or a miracle. In the case of these midwestern quiet wealth stories, the script is almost always identical. They bought a modest home in the nineteen-seventies in a neighborhood that subsequently gentrified or saw massive infrastructure expansion. They held a few blue-chip stocks through every crash.
They did not outsmart the market. They sat on a winning lottery ticket that society printed for them through suburban sprawl and restrictive zoning laws.
When financial commentators act like anyone can replicate this path by packing their lunch to work, they are committing intellectual fraud. The economic landscape that allowed a middle-income earner to amass an eight-figure net worth simply does not exist anymore. Entry-level housing costs multiple times what it did relative to median wages. Healthcare expenses eat up the surplus that used to fund brokerage accounts.
Pretending that individual virtue is the deciding factor in wealth creation allows policymakers to ignore the systemic failures that make basic financial security impossible for the current generation.
What You Should Do Instead
If you want to build wealth, stop taking financial cues from people who treated life as a waiting room for death.
First, optimize for earning capacity, not penny-pinching. You cannot cut your way to financial freedom in an inflationary environment where the cost of living floor keeps rising. Focus on high-leverage skills that allow you to command superior compensation or build equity in cash-flowing assets.
Second, deploy your capital while you are alive to enjoy it and shape the world around you. Philanthropy at death is often just tax avoidance or a failure of imagination. If you have surplus capital, put it to work in your community, fund ventures, support people who are struggling right now, or buy experiences that expand your capability.
Hoarding wealth until your heart stops beating is not a virtue. It is an exit strategy for people who were too afraid to live.
Stop looking for the secret formula in a dead man's closet. The game has changed, the rules are different, and the only thing thriftier than saving a dollar is realizing that time is the only asset you cannot compound.