Paper Wealth and the Cost of Liquid Cash
Money.
We talk about it in grand, sweeping numbers—millions, tens of millions, luxury apartments overlooking Victoria Harbour, portfolios stuffed with blue-chip equities and property deeds that look invincible on a quarterly statement. Yet cash behaves differently. Cash is heavy. Cash is stubborn. And when a person has vast wealth tied up in assets that cannot be folded into a pocket or wired at midnight without friction, the distance between looking rich and having ready money can become a fault line. In similar news, we also covered: Executing a 77-Year-Old Proves Capital Punishment Is Broken in Every Direction.
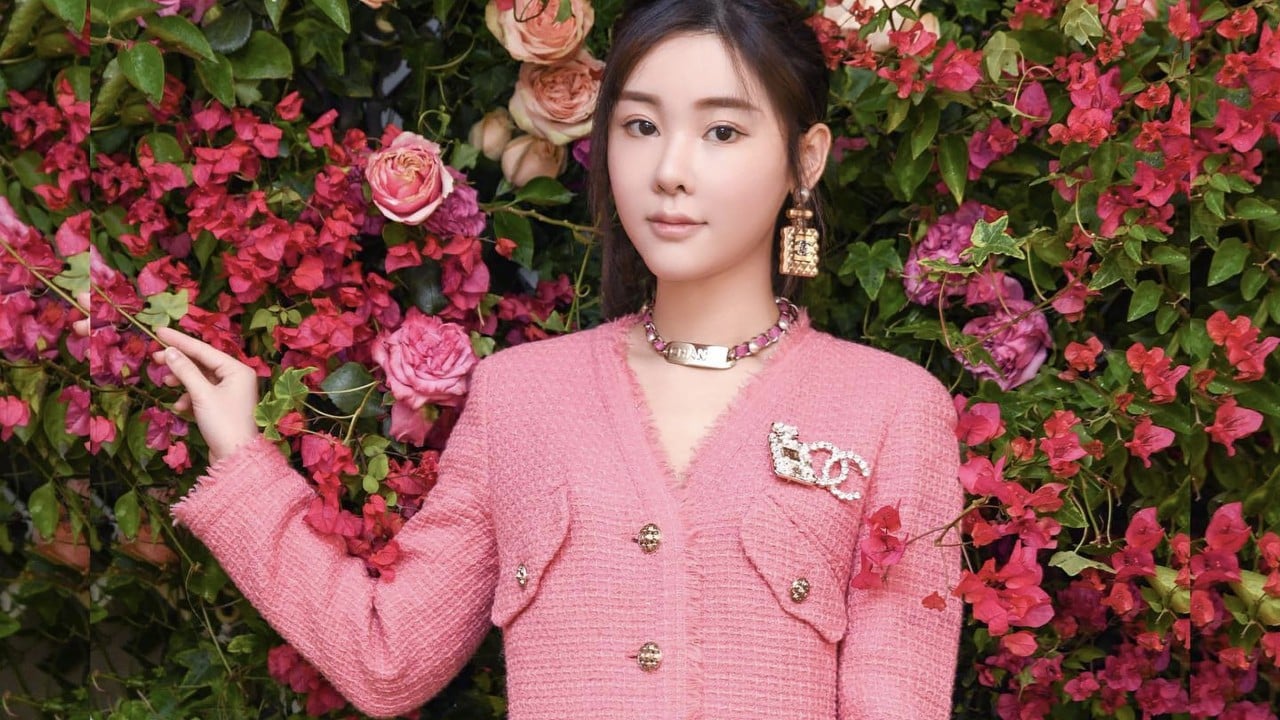
In Hong Kong murder trial coverage surrounding the killing of socialite Abby Choi, testimony emerged that she did not have enough cash in the year before her death. Details like that sound cold in a courtroom transcript. A line on a ledger. A phrase read aloud while cameras click outside a courthouse. Behind that single sentence sits a wrenching human reality: a young woman moving through glittering circles, managing high-stakes family dynamics and substantial property interests, while confronting the quiet, unglamorous pressure of liquidity.
I have spent years watching families and founders mistake net worth for safety. You walk into a glass-walled office with a view of the harbor, hear someone speak calmly about eight-figure holdings, and feel a reflex of awe. Then you sit at a kitchen table six months later and watch the same person sweat over a wire transfer, a tax bill, a loan renewal, or a family obligation because their money is locked inside bricks, contracts, or disputes. The air in the room changes. Paper wealth does not pay today's invoice by itself. Associated Press has provided coverage on this critical topic in extensive detail.
To understand why a cash crunch matters so deeply—both in ordinary households and in extreme tragedies like the Abby Choi case—we have to strip away the gloss of glamour and look at how illiquidity actually feels.
The Illusion of Being Rich on Paper
Rich.
The word invites pictures of ease. You picture someone stepping into a chauffeured car, wearing couture, never checking the balance before ordering. That picture is mostly theater.
Consider a hypothetical scenario to see how easily the illusion forms. Suppose a woman in her late twenties—let's call her Maya—owns a stake in a high-value residence and shares in family-linked holdings. On paper, she is far wealthier than almost anyone she meets at dinner. A bank might even view her as an attractive client. Yet if the property cannot be sold quickly without taking a steep discount, or if funds are entangled in trust structures, corporate accounts, or family arrangements, her actual spending power day to day is much narrower than her net worth suggests.
That gap is where stress breeds.
In courtroom reporting on the Abby Choi murder trial, prosecutors and witnesses examined financial arrangements, property dealings, and money flows in the period leading up to her death in February 2023. When testimony states that she lacked sufficient cash in the year before she died, the public often reacts with disbelief. How could someone tied to luxury real estate and high-society circles be short on cash?
Because real estate is not a checking account.
A luxury flat in a dense city like Hong Kong can represent tens of millions of Hong Kong dollars on paper, yet converting that equity into spendable cash takes time, legal sign-offs, market timing, and often the agreement of co-owners or family members. Even when assets exist, access is rarely instantaneous. Liquidity is the ability to turn an asset into usable money quickly without losing half its value in the process. Without it, a person can be asset-rich and cash-constrained at the exact same moment.
I have felt that squeeze myself early in my career when an invoice sat unpaid for ninety days while rent, payroll, and taxes kept marching forward on schedule. My stomach tightened every time my phone buzzed. My desk had contracts worth more than I had ever earned in a single year, yet my checking account felt thinner than a dime. Multiply that knot in the stomach by high-stakes family entanglements, public scrutiny, and intense personal pressure, and you begin to see why cash flow is never just an accounting detail.
When Family Money Becomes a Pressure Cooker
Money inside a family rarely moves in straight lines. It loops, doubles back, carries old promises, and picks up emotional weight with every hand it passes through.
Think of money as a metaphor for water in an old building with too many valves. If every pipe is open and clear, water reaches the top floor smoothly. If someone twists a valve shut, redirects a line into a basement tank, or argues over who owns the main pipe, pressure builds behind the blockage. Pipes groan. Joints leak. Sometimes they burst.
In high-profile cases where family ties and financial interests collide, money often sits at the center of unspoken expectations. Who paid for what? Who holds title? Who expects ongoing support, allowances, or property transfers? When cash gets tight—or when one person's cash flow does not match another person's expectations—resentment can harden fast.
Testimony in the murder trial brought those financial dynamics into sharp relief. Observers following the proceedings were not just looking at a gruesome crime; they were looking at the tangled web of money, property, and relationships that surrounded the victim in the months prior. A shortage of liquid cash in the year before her death became a focal point because cash—or the lack of it—shapes choices, leverage, and tension.
When people lack ready cash, options shrink. You cannot simply walk away cleanly from a complicated arrangement if buying out a stake, hiring independent counsel, covering living expenses, or settling obligations requires liquid funds you do not have on hand. Instead, you negotiate from a tighter corner. You rely on promises, credit, or other people's cooperation.
That vulnerability is hard to admit, especially when your public image projects effortless success. Nobody wants to post a photo from a gala and then whisper to a friend that their liquid cash is stretched thin. Keeping up appearances while managing a cash shortfall takes a quiet, exhausting toll.
Why People Ask About Cash, Wealth, and Courtroom Clues
Whenever a case like this makes headlines, readers naturally ask practical questions. Why does a detail about cash a year earlier matter in a murder trial? How can someone with valuable assets run low on liquid cash? And what does financial testimony actually prove?
Let's weave those questions straight into the reality of how cases and finances work.
First, a cash shortage a year before a tragedy does not by itself explain a murder. A murder requires motive, intent, opportunity, and criminal acts proved beyond reasonable doubt in court. Financial strain is not a crime, and plenty of people experience tight cash flow without violence ever entering the picture. Prosecutors and defense teams look at financial history because money trails show relationships, dependencies, disputes, and incentives over time. A year is a long runway in financial life—long enough for property plans to shift, loans or advances to be sought, and friction to build.
Second, running low on cash despite owning valuable assets is far more common than outsiders assume. Property taxes, management fees, mortgage interest, insurance, legal fees, and everyday living costs do not care that your equity is sitting in a prime address. If capital is tied up in illiquid holdings or disputed structures, a person can face a genuine cash crunch while still appearing wealthy.
Third, financial evidence in court is rarely neat. Bank statements, property records, and witness accounts often tell partial stories that only make sense when placed side by side. A witness might testify about a shortage of cash, while another explains how funds were tied up or routed. Jurors and observers have to separate speculation from verified testimony.
I find myself pausing here and admitting something honest: financial records can be dizzying. Even seasoned journalists, accountants, and lawyers sometimes stare at a chart of transfers and feel a wave of fatigue. Numbers look objective on paper, yet human beings attach stories, grievances, and fears to every dollar. When a story involves both high-society wealth and violent death, the temptation to oversimplify is huge. Resist that temptation. Truth lives in careful facts, not easy slogans.
The Invisible Stakes Behind Every Ledger
Every ledger has a human shadow.
Look past the headlines for a moment and picture the ordinary rhythm of a life. A calendar full of meetings. Messages arriving at all hours. Decisions about homes, children, family members, and futures. When cash is abundant and liquid, friction stays low; small problems stay small because you have room to breathe. When cash is scarce, friction rises everywhere. Every delay feels heavier. Every disagreement carries a price tag.
History offers plenty of proof of this pattern across centuries and cultures. Aristocrats with crumbling estates and no coin in their pockets. Merchant families with warehouses full of goods during a credit freeze. Modern entrepreneurs with sky-high valuations and three weeks of runway left in the bank. The setting changes from silk robes to tailored suits, from ledgers written with dip pens to spreadsheets glowing in the dark, yet the human ache is remarkably consistent: owning something precious while lacking the immediate means to move freely.
Why does that ache stay hidden until something breaks?
Because shame keeps people quiet. If you are perceived as affluent, admitting you are short on cash feels like losing status. People smile, nod, talk about future plans, and quietly juggle obligations behind closed doors. By the time outsiders notice a crack in the facade, the pressure inside has often been building for months.
In the coverage of Abby Choi's murder trial, the revelation that she did not have enough cash in the year before her death hit readers like a sudden cold draft. It reminded everyone watching that surface wealth and day-to-day liquidity are not twins. You can stand inside a world of luxury and still feel the pinch of scarce cash.
Carrying the Lesson Forward
So what stays with you after the courtroom doors close and the news cycle moves on?
Cash.
It is just paper or digits on a screen, yet it buys time, breathing room, and independence. Watching a case unfold where liquid cash was reportedly tight in the year leading up to a fatal tragedy forces a sober look at how money operates beneath glamorous surfaces—and how easily financial tension can weave into already fraught human lives.
You do not need a penthouse or a tabloid headline to feel the weight of that lesson. You only need to remember how different it feels to have cash in hand when the unexpected hits, compared to pointing at an asset you cannot quickly touch.
A single unpaid bill on a rainy Tuesday afternoon can teach you more about liquidity than a dozen finance textbooks ever will.